Wind and hurricane insurance for rental properties
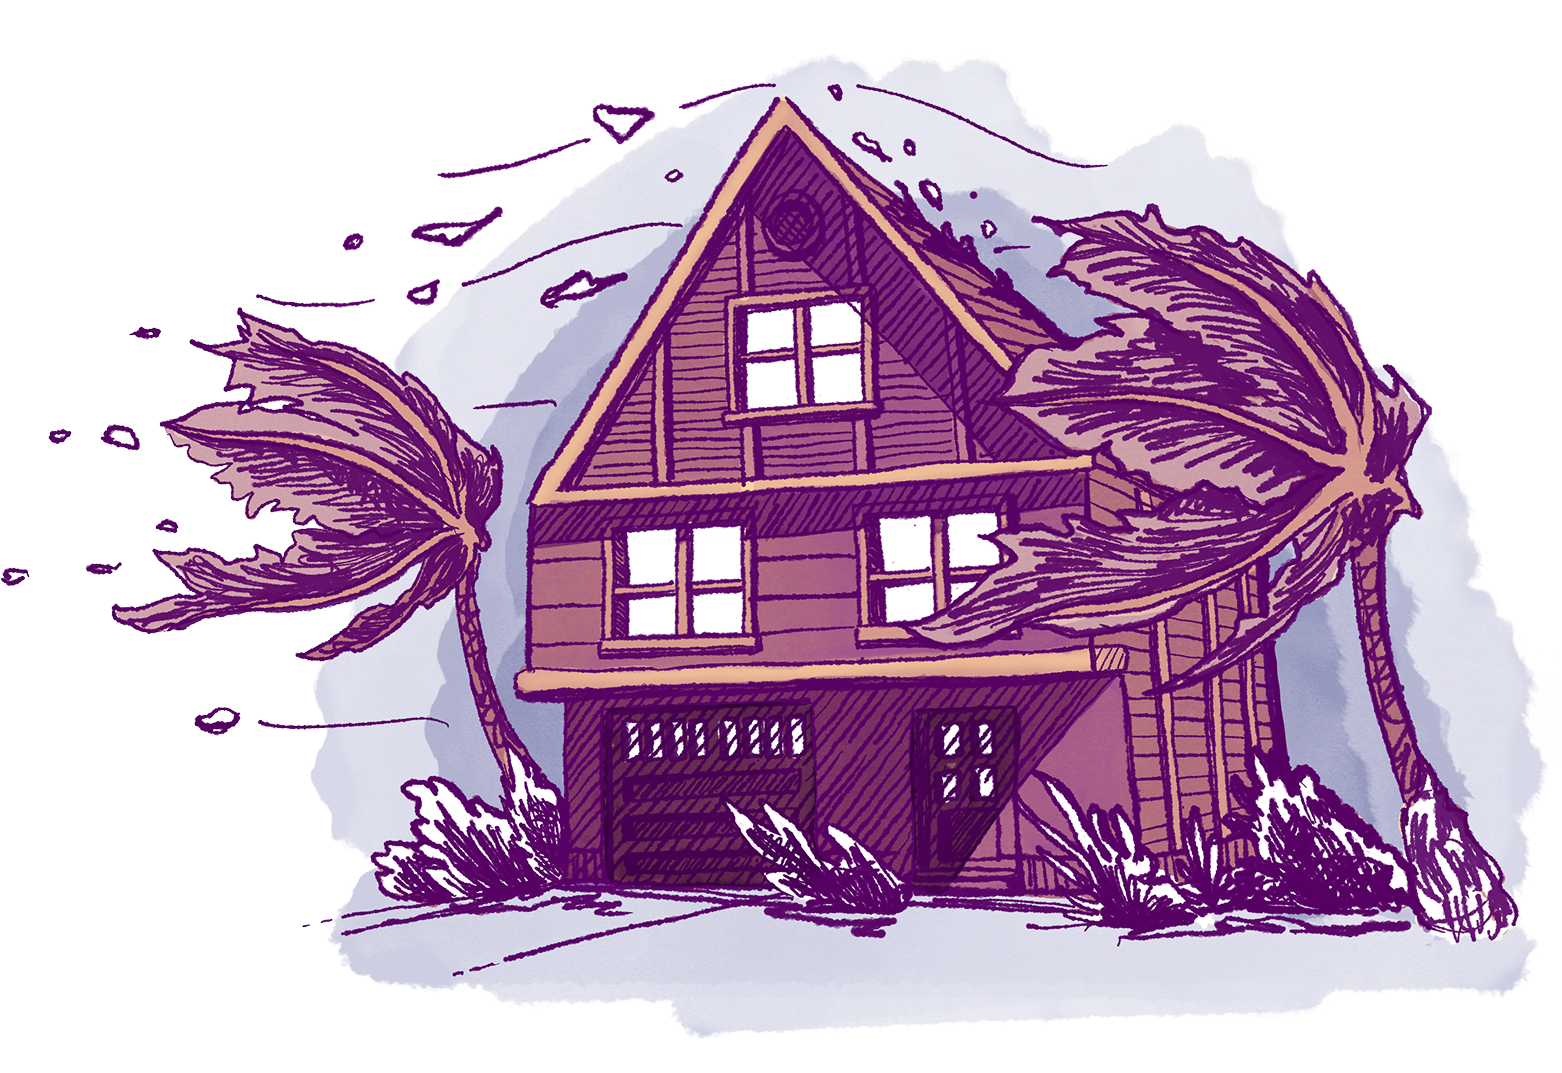
Steadily covers wind and hurricane damage to the structure of your rental, from a stripped roof and broken windows to siding torn loose and a tree through the wall, plus the rental income you lose while it's repaired.
Does landlord insurance cover wind and hurricane damage?
Yes. Landlord insurance covers wind and hurricane damage to the structure of your rental, including a torn-off roof, broken windows, ripped siding, and anything the wind sends through a wall, along with the rent you lose while the place is repaired, up to your policy limits. The big exception is water: flooding and hurricane storm surge are excluded and need a separate flood policy.
Types of wind and hurricane damage covered
- Structural wind and hurricane damage
- Roof, shingle, and exterior damage
- Broken windows and doors blown off their frames
- Damage from wind-driven debris and fallen trees
- Lost rental income while the unit is uninhabitable
Your roof is part of the dwelling, so when a windstorm peels back shingles or a hurricane strips the whole thing, the repair falls under structural coverage. The same goes for siding, gutters, and anything bolted to the outside of the building. If a neighbor's oak comes down on your roof or a flying branch punches through a window, the damage and the debris removal are generally covered, and if that damage makes the unit unlivable, loss of rent picks up the income you'd otherwise lose while contractors work.
Wind-driven rain is where it gets a little nuanced. If a storm tears an opening in the roof or a window and rain gets in through that opening, the interior water damage usually rides along with the wind claim. Rain that seeps in through an old, worn roof that was already failing is a different story, and we'll get to that below.
Wind versus flood: the line that catches coastal landlords out
Here's the thing most owners learn the hard way after a hurricane: your landlord policy and a flood policy split the storm right down the middle. Wind, and the rain that follows it into a building the storm has already opened up, sits with your landlord insurance. Water that rises from the ground, storm surge, an overflowing creek, streets that turn into rivers, is flood, and flood is never covered by a standard landlord policy no matter how the water got there.
That distinction decides who pays after a named storm, and it's why a coastal rental really needs both. Steadily's wind and hurricane coverage handles the wind side; flood you carry separately through the National Flood Insurance Program or a private flood policy. Carrying one and assuming it covers the other is the single most expensive mistake we see landlords make in coastal markets.
Wind and hurricane damage that landlord insurance may not cover
The coverage is broad, but a few things sit outside it. These are the exclusions that surprise landlords most:
- Flood and storm surge, which require a separate flood policy
- Gradual wear and tear, or a roof that was already at the end of its life before the storm
- Vacant properties, typically defined as unoccupied for more than 30 to 60 days
- Cosmetic damage in some coastal policies, where dented-but-functional metal or shingles may be excluded
What wind and hurricane coverage pays for, and what it doesn't
Wind and hurricane claims are some of the largest a landlord will ever file, and they're also where the fine print bites hardest, especially the deductible and the flood exclusion. Here's what your policy actually pays for, and where it stops.
How much wind and hurricane coverage do I need?
Your dwelling limit should equal what it would actually cost to rebuild the property today, not its market value and not what you paid for it. On the coast that number is often higher than owners expect, because demand surges after a big storm and labor and materials get scarce and pricey exactly when everyone needs a contractor at once. Set the limit to a real, current rebuild estimate and revisit it every couple of years.
For personal property, inventory what you actually own at the rental: appliances you supply, maintenance equipment, anything in the common areas. Most policies include some personal property coverage, so make sure the limit can replace what you keep on site. And don't skip loss of rent. If a hurricane puts a unit out of commission for four months, that coverage is what keeps the mortgage paid while it sits empty.
How hurricane and named-storm deductibles actually work
This is the part of a coastal policy that catches people off guard. In hurricane-prone states, wind losses don't run through your flat dollar deductible. They run through a separate hurricane or named-storm deductible, a percentage of your dwelling coverage that kicks in once the National Hurricane Center names the storm. It's typically 2% to 10%, and in the highest-risk coastal counties it starts at 5%.
The math matters. On a rental insured for $400,000, a 5% hurricane deductible is $20,000 out of your pocket before the policy pays a dime, which is a very different number than the $1,000 you might be picturing. Some states let you buy that percentage down; some cap it. Either way, read the declarations page before storm season and know your real out-of-pocket, because finding out mid-claim is a rough way to learn it.
Wind coverage where the standard market has pulled back
The highest-risk coastal markets are their own animal. Standard carriers have retreated from a lot of them, dropping policies and refusing new business in whole zip codes, and in many coastal areas wind gets carved right out of the base property policy, sold instead as a separate wind-only policy or picked up through a state insurer of last resort. That leaves plenty of landlords underinsured without realizing it, or paying a fortune for patchwork coverage.
Steadily offers wind and hurricane coverage for rental properties, and because what's available and what it costs depend so heavily on where the property sits, a quote is the fastest way to see your real options and your real number, deductible and all. If your rental is in a hurricane zone or anywhere a named storm is a when-not-if, that beats guessing at what the shrinking standard market will offer.
What drives the cost of wind insurance on a rental
Location leads, and it isn't close. A rental three blocks from the water in a hurricane zone costs far more to insure against wind than the same house fifty miles inland. After that, the roof is the biggest lever: its age, its shape, and what it's made of. Insurers love a newer roof, and they favor a hip roof, the kind that slopes on all four sides, because it sheds wind better than a gable, and they'll price a 20-year-old roof in a coastal county like the liability it is.
The good news is that wind is one of the few perils where you can genuinely buy the price down. A wind mitigation inspection documents the features that help a home stand up to a storm, things like hurricane straps, a well-anchored roof deck, and impact-rated windows and doors, and those credits can cut the wind portion of your premium substantially. In higher-risk states you may also go through a four-point inspection of the roof, electrical, plumbing, and HVAC as part of getting covered. If you've done the work, or you're weighing whether to, get the inspection and put the savings in writing.
What wind and hurricane damage looks like across real rental properties
Frequently Asked Questions
Does landlord insurance cover hurricane damage?
Yes, for the wind side of a hurricane: damage to the roof, siding, windows, and structure, plus lost rent while you repair. It does not cover flooding or storm surge, though. That water damage needs a separate flood policy, even during the same storm.
Is there a separate deductible for hurricane or windstorm claims?
In most coastal and hurricane-prone states, yes. Wind losses run through a percentage-based hurricane or named-storm deductible, often 2% to 10% of your dwelling limit and 5% in the highest-risk coastal counties, rather than your flat deductible. On a $300,000 dwelling, a 5% deductible means $15,000 out of pocket before coverage starts.
Does wind or hurricane insurance cover flooding?
No. Wind and hurricane coverage handles wind-driven damage, but rising water and storm surge are classified as flood, which is excluded from every standard landlord policy. You would cover that separately through the National Flood Insurance Program or a private flood insurer.
Do I need a separate windstorm policy?
Sometimes. In many high-risk coastal areas, wind is excluded from the base property policy and sold separately as a wind-only policy or written through a state insurer of last resort. A single Steadily quote can tell you whether wind is included for your property or whether you need a standalone windstorm policy.
How can I lower my wind insurance premium?
Get a wind mitigation inspection. It documents storm-resistant features like hurricane straps, a well-anchored roof deck, and impact-rated windows, and many states require carriers to give credits for them. A newer roof and a hip-roof design help too, and bundling wind into a full landlord policy usually beats buying it piecemeal.
What else does Steadily cover?
We cover a wide range of risks, or you can choose a limited set of coverages for a lower premium

Riot & civil commotion
Covers damage to your rental property caused by riots, civil unrest, and public disturbances.

Vandalism & burglary
Covers damage made to your rental property by a burglar or a vandal, such as broken windows or defacements made to walls or exterior structures.
Loss of rent
Loss of rent insurance, also called fair rental value coverage, replaces the rental income you lose when a covered event makes your rental uninhabitable.
Storm and hail
Storm and hail damage insurance for landlords covers roof punctures, siding, windows, and wind damage to your rental. See what’s covered, deductibles, and how much coverage you need.

Water
Water damage insurance for rental properties covers burst pipes, roof leaks, appliance overflows, and sewer backups with an endorsement, plus lost rent. See what’s covered, the exclusions, and how much you need.

Legal liability
Landlord liability insurance pays medical bills, legal defense, and settlements when a tenant or visitor is injured at your rental. Steadily writes $300K to $2M of liability into every landlord policy in all 50 states. Quote in two minutes.
Fire
Fire insurance for rental properties covers structural fire and smoke damage, your personal property, and lost rent while repairs are underway. See what’s covered, exclusions, and how much coverage you need.
What wind and hurricane damage looks like across real rental properties

Insurance basics